IRC § 263(a) vs. the $25 Business Gift Limit: How Private Equity & M&A Controllers Document Deal Closing Crates
A practical accounting and procurement guide distinguishing capitalized transaction facilitation costs under Treas. Reg. § 1.263(a)-5 from ordinary IRC § 274(b)(1) promotional gifts.
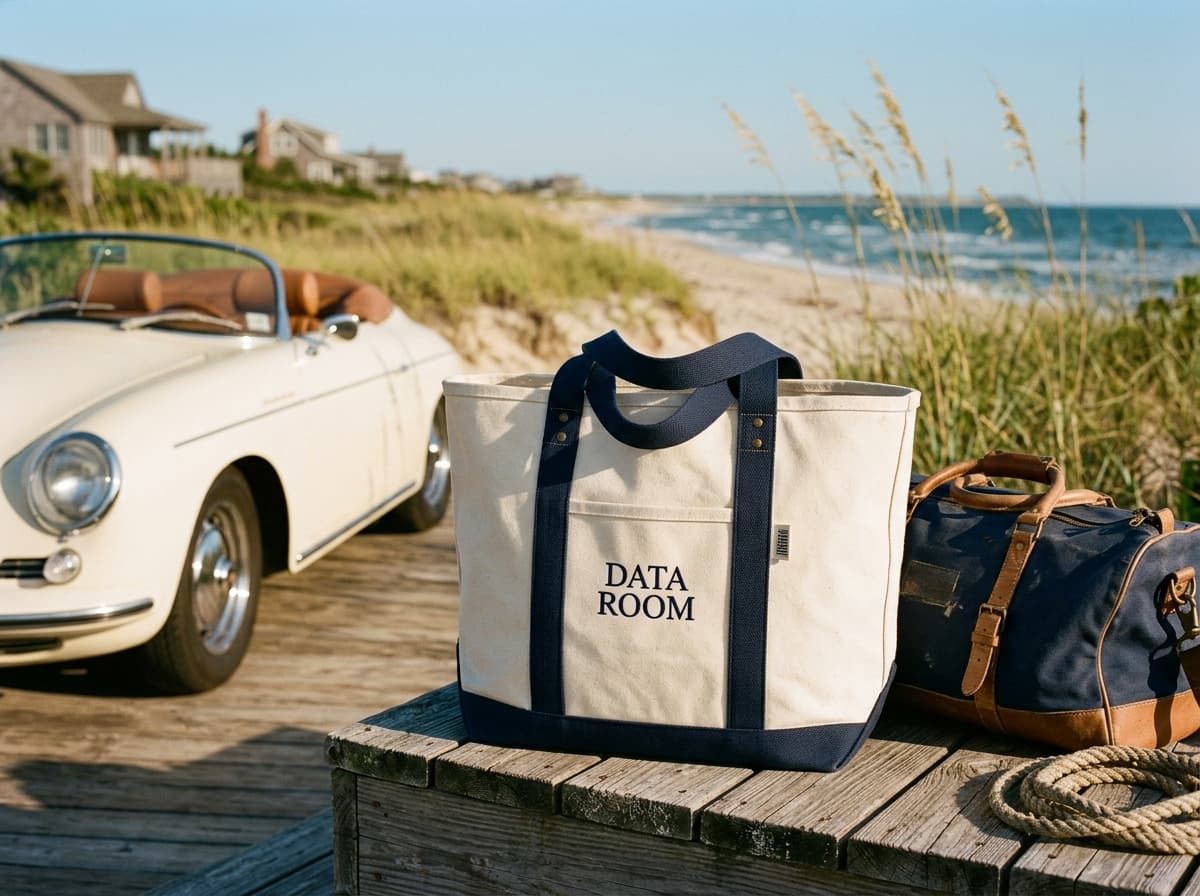
Few numbers in federal tax accounting create more confusion on a deal floor than $25. Enacted in the Revenue Act of 1962 and frozen unindexed for over six decades, IRC § 274(b)(1) limits current-year ordinary business deductions for general promotional gifts to $25 per individual recipient per year. Yet across thousands of buyouts, debt syndications, and strategic mergers tracked in PitchBook and Bain 2026 private capital benchmarks, sponsors, investment banks, and corporate acquirers routinely commission $145 to $300+ per-set closing commemoratives without triggering $25 promotional gift disallowances—because deal tombstones and transaction-specific Closing Crates are governed by a fundamentally different statutory regime.
Capitalized Transaction Facilitation Under IRC § 263(a) & Treas. Reg. § 1.263(a)-5
Under IRC § 263(a) and the final "INDOPCO regulations" codified at Treas. Reg. § 1.263(a)-5, amounts paid in the process of investigating, pursuing, or closing an acquisition of a trade or business, a change in capital structure, a borrowing, or a stock issuance are classified as capitalized transaction facilitation costs added to basis (or amortized over debt term for financing costs) rather than deducted as ordinary SG&A promotional gifts. Crucially, to substantiate transaction nexus during fund audit review, controllers verify three evidentiary markers: (1) permanent transaction-specific customization (deal codename, target/SPV initials, and closing quarter), (2) distribution restricted to the deal working group and counterparty principals, and (3) invoice coding directly to the acquisition vehicle, client matter number, or deal facilitation ledger.
"When an associate submits an uncoded retail receipt for twenty sweaters, audit flags IRC § 274(b)(1) immediately; when an invoice arrives coded to Project Meridian with permanent Q4 closing embroidery and an IRC § 263(a) Deal Expense Memorandum, it schedules cleanly onto the transaction closing checklist." — Chief Financial Officer & Fund Controller, $3.4B Lower-Middle-Market Buyout Sponsor
| Statutory & Procurement Dimension | Transaction-Tied Closing Crate (IRC § 263(a)) | Ordinary Promotional Gift (IRC § 274(b)(1)) | Overseas Lucite Tombstone (IRC § 263(a)) |
|---|---|---|---|
| Governing Code Section | IRC § 263(a) & Treas. Reg. § 1.263(a)-5 | IRC § 274(b)(1) (ordinary SG&A marketing) | IRC § 263(a) & Treas. Reg. § 1.263(a)-5 |
| Per-Recipient Statutory Cap | 100% capitalized to deal / debt facilitation basis | $25.00 / recipient / year deduction limit | 100% capitalized to deal / debt facilitation basis |
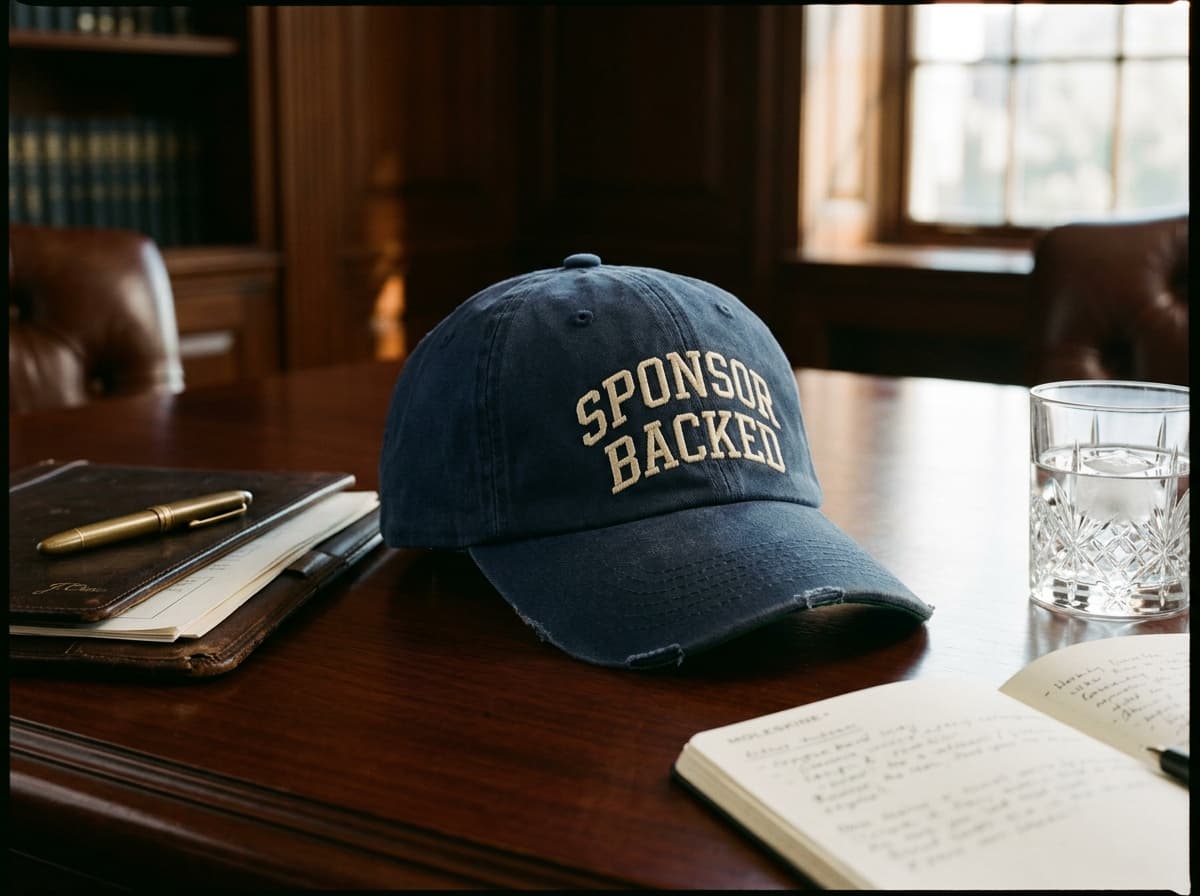
| Customization Evidence | Embroidered deal codename + close quarter (CLOSED Q4) | Generic company logo or unbranded retail item | Embedded deal tombstone text |
| Production Lead Time | 7 business days (Sponsor Backed Dallas Atelier) | Variable retail / 40% merch discard rate | 15–25 business days overseas curing |
| Recipient Retention & Cost | 69%–85% retention at $145–$185 / set | Low retention if cheap; disallowed above $25 | $210–$325+ / unit; zero wearable utility |
Automated Audit Readiness: The Printable Deal Expense Memorandum
To eliminate back-and-forth between deal VPs and fund accounting, every Closing Crate configured on /deal-toy automatically generates a printable Deal Expense Memorandum alongside Net-30 ACH, wire, or Stripe payment receipts. Pre-populated with transaction codename, close quarter, itemized unit count (12–24, 25–49, or 50+ sets), Dallas manufacturing specs, and explicit citations to IRC § 263(a) and Treas. Reg. § 1.263(a)-5, the memorandum gives fund controllers and external auditors turnkey workpaper documentation (provided for institutional procurement reference; always consult fund or corporate tax counsel for transaction-specific treatment).
Institutional Briefing
Executive Q&A
Why does the $25 IRC § 274(b)(1) gift limit apply to holiday swag but not capitalized M&A closing crates?
IRC § 274(b)(1) caps current-year ordinary business expense deductions (§ 162) for general promotional gifts at $25 per recipient, whereas commemorative closing items permanently customized with a closed deal codename and date for transaction participants are documented as capitalized transaction facilitation costs under IRC § 263(a) and Treas. Reg. § 1.263(a)-5.
What documentation does a private equity fund controller need to book a Closing Crate to Deal Co.?
Controllers typically require an itemized corporate invoice referencing the acquisition SPV or deal codename, verification of permanent transaction-specific customization, and a Closing Expense Memo—all three of which are generated automatically on sponsorbacked.com/deal-toy.
What if a firm wants a non-deal promotional gift that stays strictly below the $25 IRC § 274(b)(1) cap?
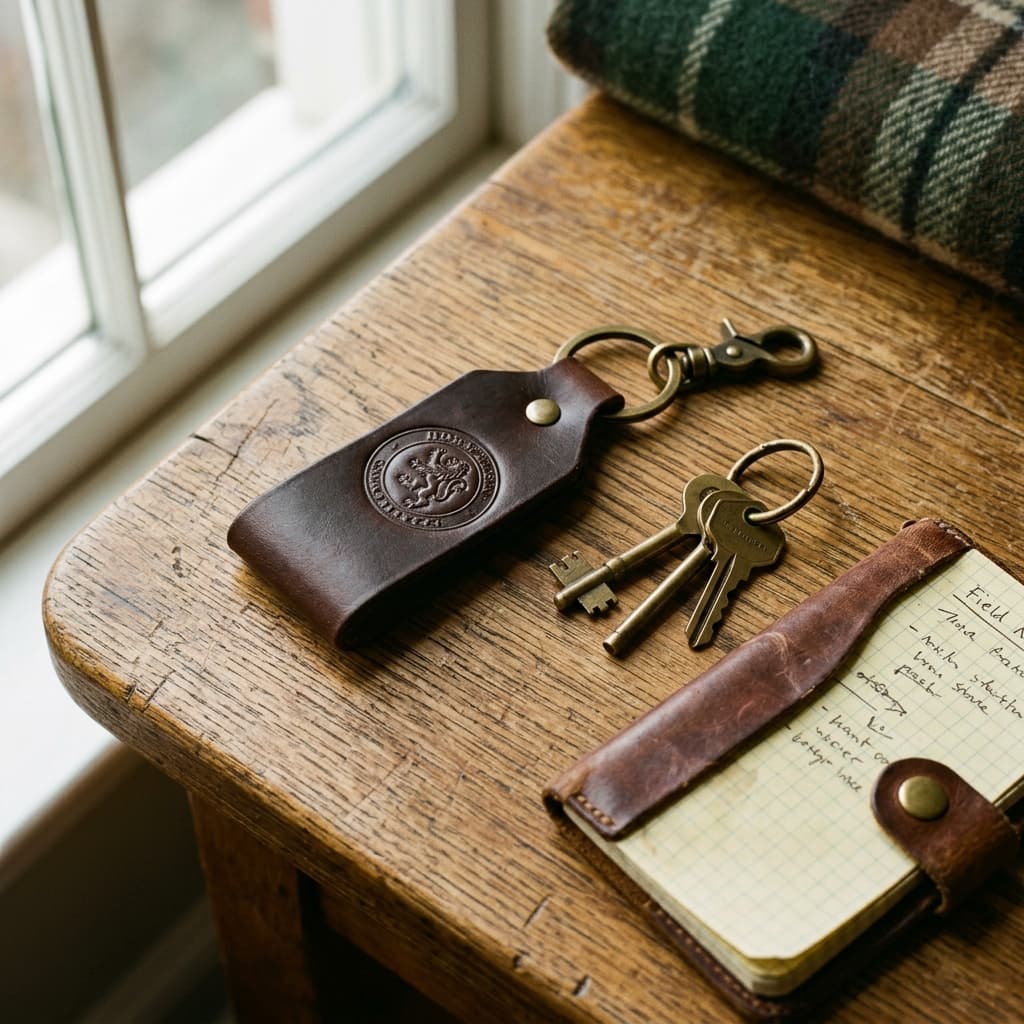
For general non-transaction gifting, our Chicago Horween Chromexcel Leather Crest Key Fob is priced at $20.00 USD—remaining below the $25 IRC § 274(b)(1) ceiling (note that under IRC § 274(b)(1), incidental engraving/packaging and shipping generally do not count toward the $25 item cost when separately stated; consult your tax advisor).
Dallas Atelier Specifications
Referenced Pieces
Institutional B2B Mandates · IRC § 263(a) Ready
Commission Bespoke Closing Crates in 7 Business Days
Configure custom stone-washed chino caps, monogrammed 16 oz duck canvas boat totes, and Chicago Horween leather carry goods—stitched in Dallas with single-CSV multi-address dispatch and an automated Deal Expense Memorandum.